Conventional loans
Private mortgage insurance may apply when the down payment is less than 20%. The cost depends on factors such as credit, loan-to-value ratio, coverage, and loan structure. Cancellation rules may apply as equity grows.
Loan Programs
Mortgage insurance generally protects the lender when a borrower has less equity in the home. The name, cost, and rules depend on the loan program, so comparing only the mortgage-insurance line can be misleading.
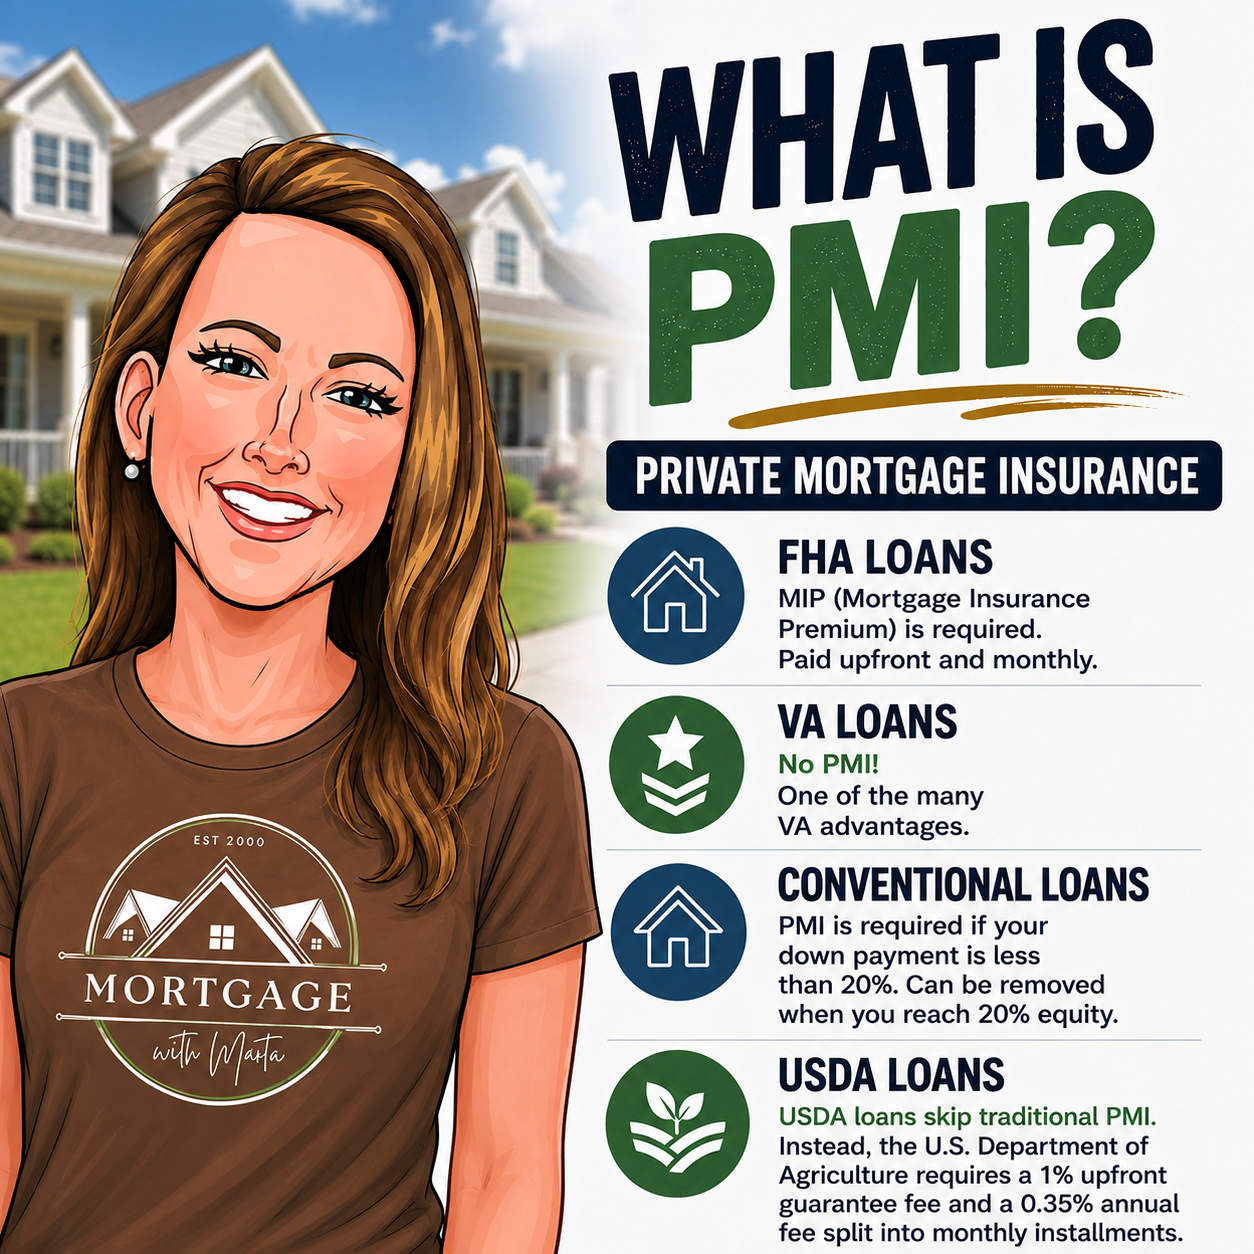
Private mortgage insurance may apply when the down payment is less than 20%. The cost depends on factors such as credit, loan-to-value ratio, coverage, and loan structure. Cancellation rules may apply as equity grows.
FHA financing generally includes an upfront mortgage insurance premium and an annual mortgage insurance premium collected monthly. How long the monthly premium remains depends on the original loan-to-value ratio and loan term.
VA loans do not have monthly mortgage insurance. A one-time VA funding fee may apply unless the eligible borrower qualifies for an exemption.
USDA guaranteed loans use an upfront guarantee fee and an annual fee collected monthly instead of traditional PMI. Current fee percentages can change, so the final comparison should use the actual loan estimate.
Do not choose a program by PMI alone. Compare the interest rate, principal and interest, mortgage insurance or guarantee fees, taxes, homeowners insurance, cash to close, and total long-term cost.
Written by Marta Lillard
Mortgage Broker · First Coast Mortgage Funding · NMLS #879436 · Licensed in Florida and Georgia
Questions about your options?