The completion date matters
The applicable clock may begin at discharge, dismissal, sale, deed transfer, or another documented completion date. The credit report alone may not show the date underwriting needs.
Credit and Income
Bankruptcy, foreclosure, deed in lieu, or short sale does not always mean your homeownership journey is over. Waiting periods vary by event, loan program, dates, documentation, and any eligible extenuating circumstances.
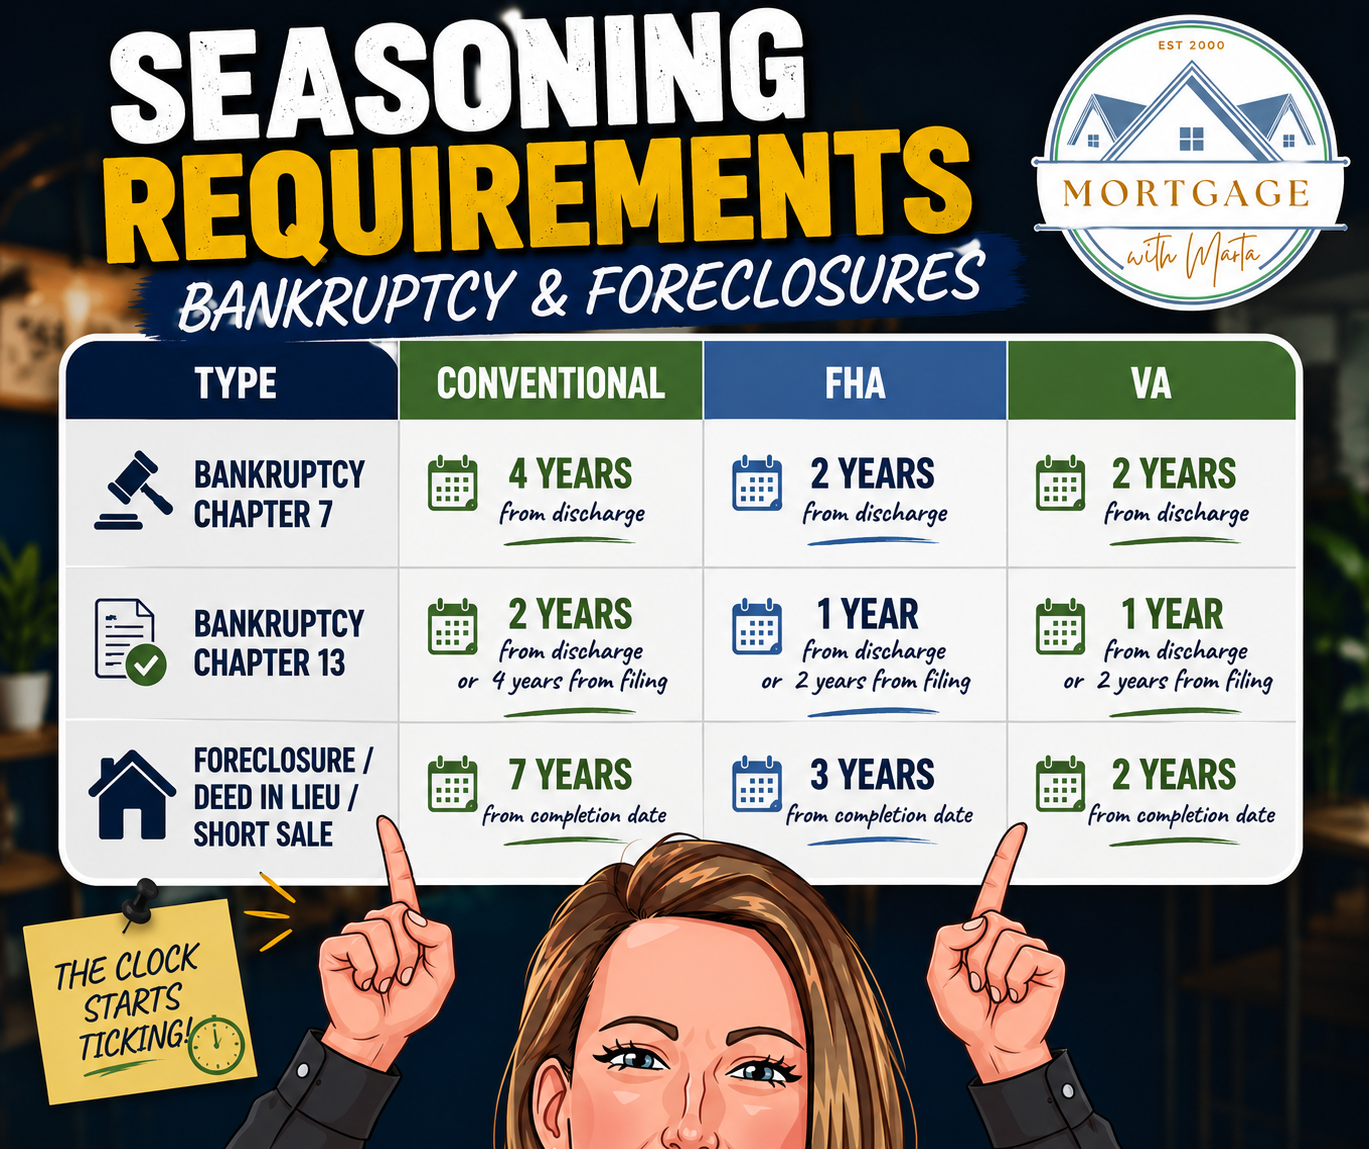
The applicable clock may begin at discharge, dismissal, sale, deed transfer, or another documented completion date. The credit report alone may not show the date underwriting needs.
Conventional, FHA, VA, USDA, and non-QM programs have different requirements. Chapter 7 and Chapter 13 bankruptcies may also be treated differently.
A completed waiting period does not guarantee approval. Re-established credit, payment history, income, assets, debt-to-income ratio, and the full loan file still count.
Gather the discharge, dismissal, foreclosure, deed, or short-sale documents and let me review the actual timeline. There may be a responsible path sooner than you think.
Written by Marta Lillard
Mortgage Broker · First Coast Mortgage Funding · NMLS #879436 · Licensed in Florida and Georgia
Questions about your options?