01Conventional loans
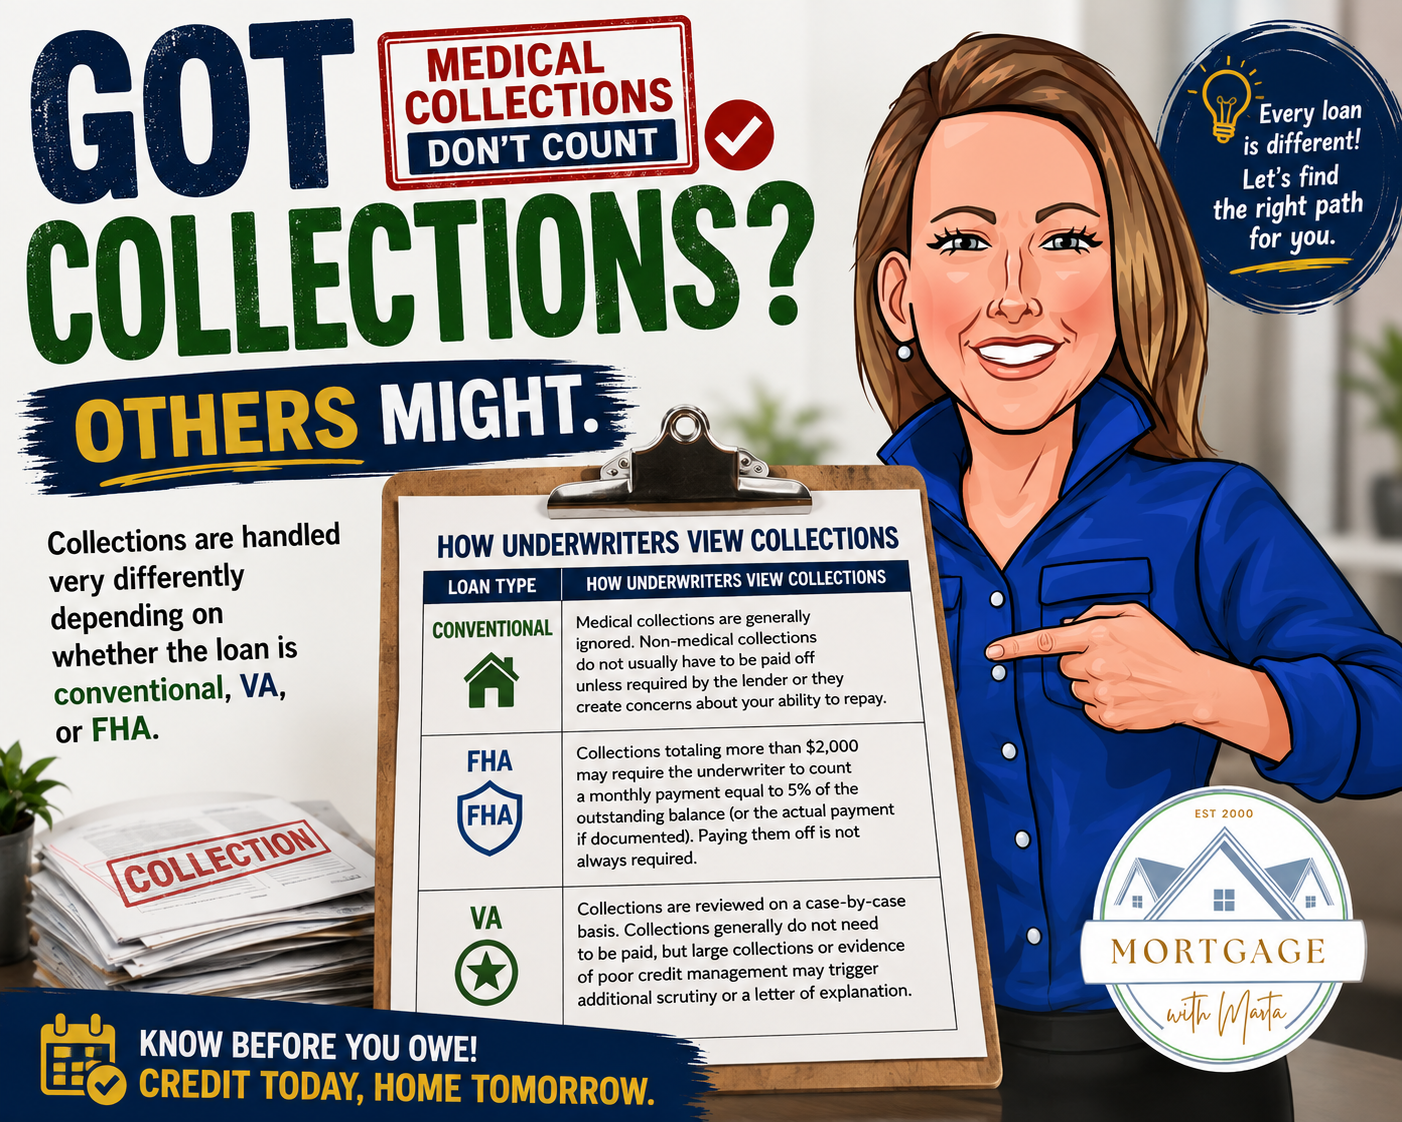
Medical collections are generally not required to be paid off for conventional financing. Other collection accounts may also remain unpaid in many primary-residence scenarios, subject to the full underwriting review and lender requirements.
02FHA loans
Medical collections are generally excluded from FHA collection calculations. If nonmedical collections total more than $2,000, the lender may need to use a documented payment arrangement or count 5% of the outstanding balance as a monthly obligation. Paying everything off is not always required.
03VA loans
VA collections are reviewed case by case. Large, recent, or unresolved collections may require additional explanation or affect the overall credit decision, but they do not automatically require payoff.
04Do not start paying blindly
Before paying or settling collections, talk with your loan officer. The strategy that helps one loan program may do absolutely nothing for another, and sometimes paying the wrong account can create a new problem.