How grossing up works
The lender applies the percentage allowed by the loan program to eligible nontaxable income. For example, $1,000 grossed up by 15% becomes $1,150 of qualifying income.
Credit and Income
Some types of verified tax-free income may be increased for mortgage qualifying because taxes are not taken out. That extra qualifying income can improve your debt-to-income ratio and sometimes turn a no into a yes.
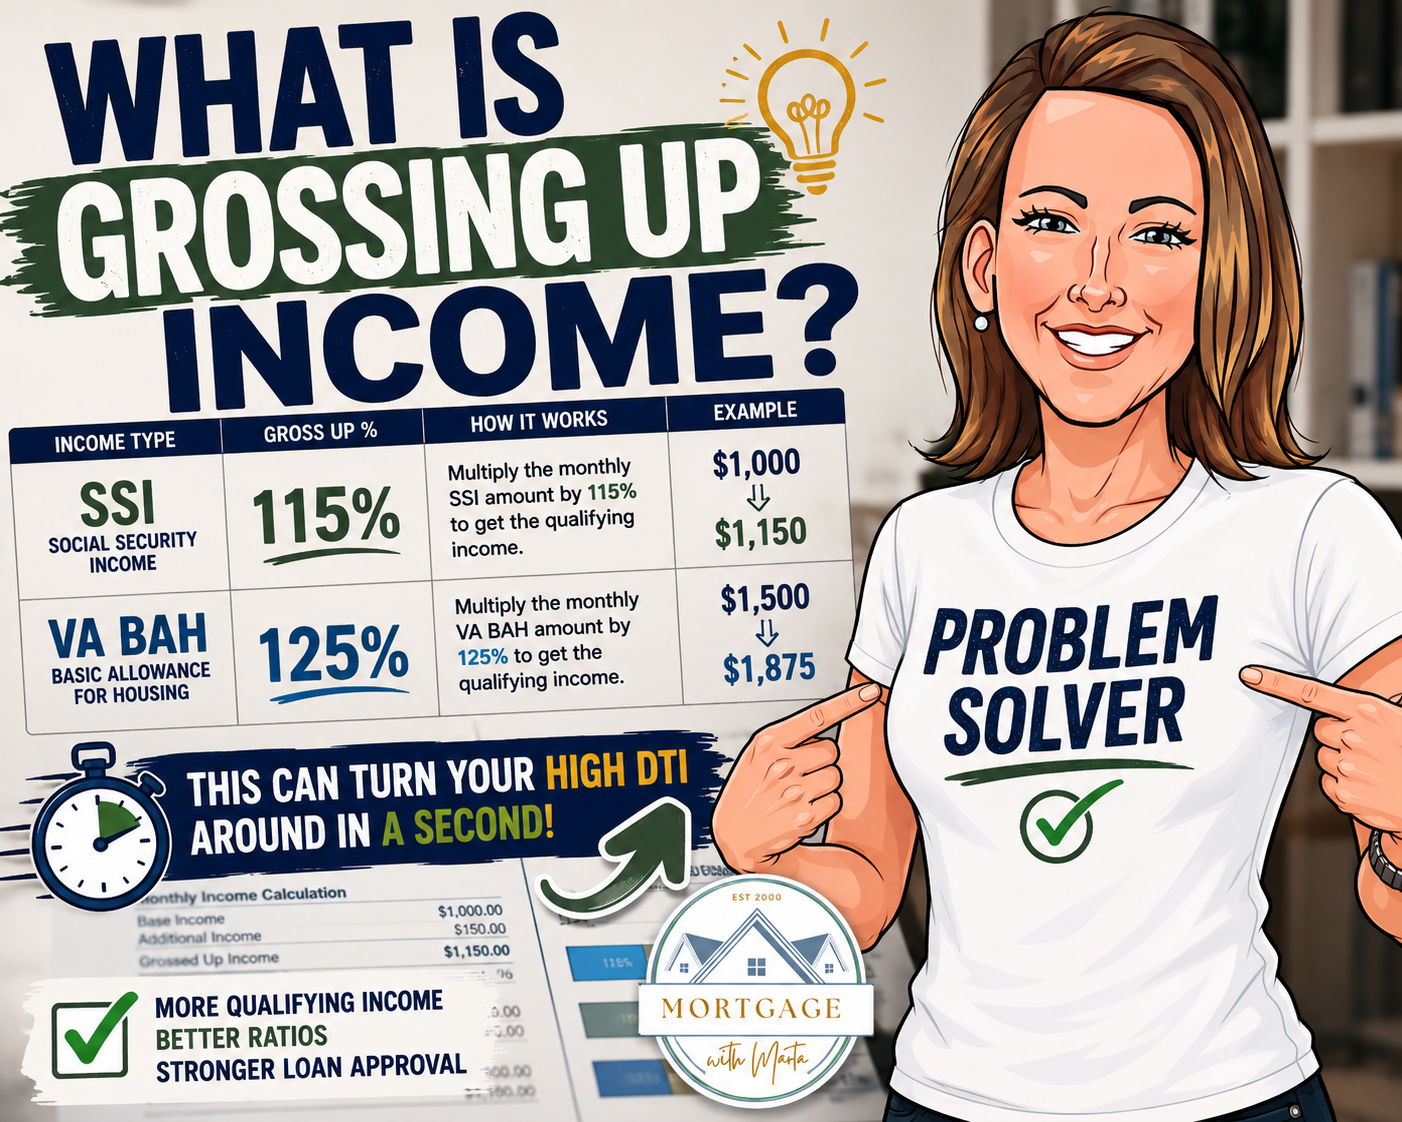
The lender applies the percentage allowed by the loan program to eligible nontaxable income. For example, $1,000 grossed up by 15% becomes $1,150 of qualifying income.
Social Security income may often be grossed up by 15%, while eligible nontaxable VA benefits, including BAH, may often be grossed up by 25%. The amount depends on the program, documentation, and whether the income is verified as tax-free.
More usable income can lower your debt-to-income ratio and strengthen the loan calculation. It does not change the money you actually receive. It only changes how qualifying income is calculated.
If your DTI looks high, do not assume the answer is no. Mortgage math is weird, and a careful review of every eligible income source can make a real difference.
Written by Marta Lillard
Mortgage Broker · First Coast Mortgage Funding · NMLS #879436 · Licensed in Florida and Georgia
Questions about your options?