W-2 employees
Lenders generally begin with gross pay before taxes and payroll deductions, then evaluate pay type, history, stability, and continuance.
Credit and Income
W-2 and self-employed income are not analyzed the same way. The amount deposited into your bank account is not automatically the income used to qualify.
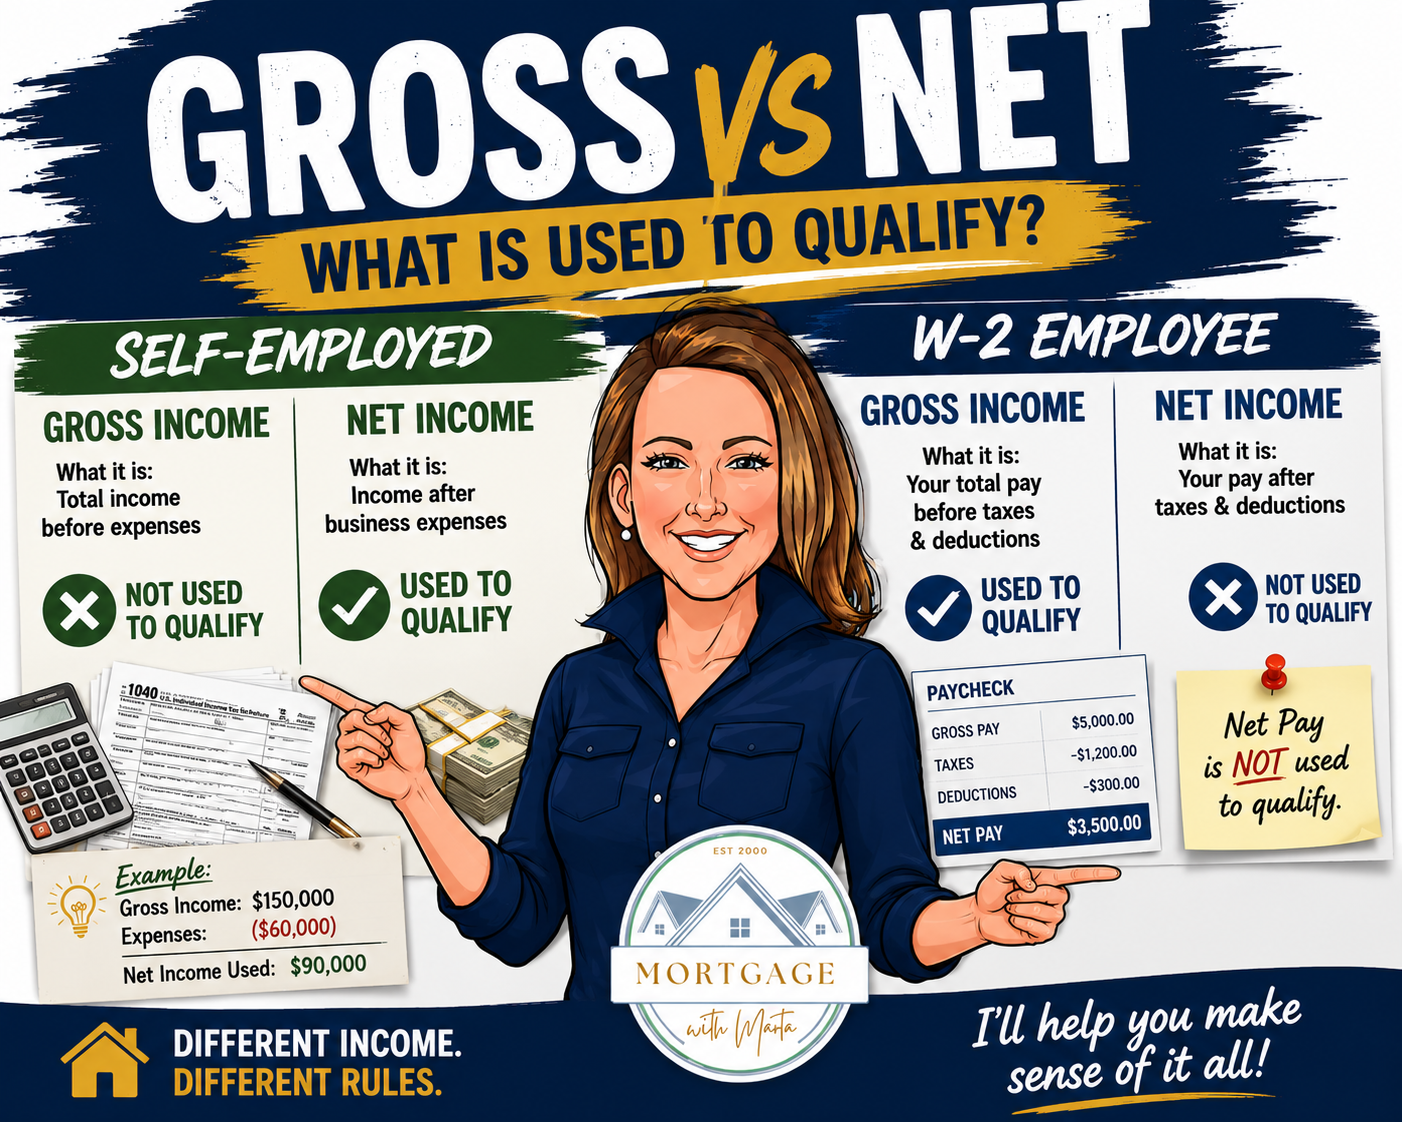
Lenders generally begin with gross pay before taxes and payroll deductions, then evaluate pay type, history, stability, and continuance.
Lenders analyze tax returns and business documents to determine qualifying income after eligible business expenses, with program-specific adjustments and possible add-backs.
Tax deductions may reduce taxable income and may also reduce mortgage qualifying income. Some noncash or eligible expenses may be added back under program rules.
Coordinate with a qualified tax professional and your loan officer before making business or tax decisions based only on mortgage qualification.
Written by Marta Lillard
Mortgage Broker · First Coast Mortgage Funding · NMLS #879436 · Licensed in Florida and Georgia
Questions about your options?